State: Required
Massachusetts: The Rules Your Auto Policy Must Follow
Massachusetts builds its auto policy around four compulsory parts, including personal injury protection and uninsured motorist coverage, and raised the compulsory limits on July 1, 2025. It also narrows the reasons a company may cancel. Here is what that means for your policy.
By PolicyBrook Editorial Team Updated 4-minute read
Declarations
Massachusetts- UM/UIM rule
- Required
- Minimum liability
- 25/50/30
- Insurer cancellation notice
- 20 days
- Nonrenewal notice
- 45 days
In brief
Every Massachusetts policy written or renewed since July 1, 2025 must carry at least $25,000/$50,000 for bodily injury to others, $30,000 for damage to someone else's property, $8,000 of personal injury protection, and uninsured motorist coverage of $25,000/$50,000. These parts are compulsory, so UM cannot be rejected. An insurer may cancel midterm only for the reasons in 211 CMR 97.00, with at least 20 days' written notice, and must send a nonrenewal notice at least 45 days before the policy expires. The Division of Insurance oversees these rules.
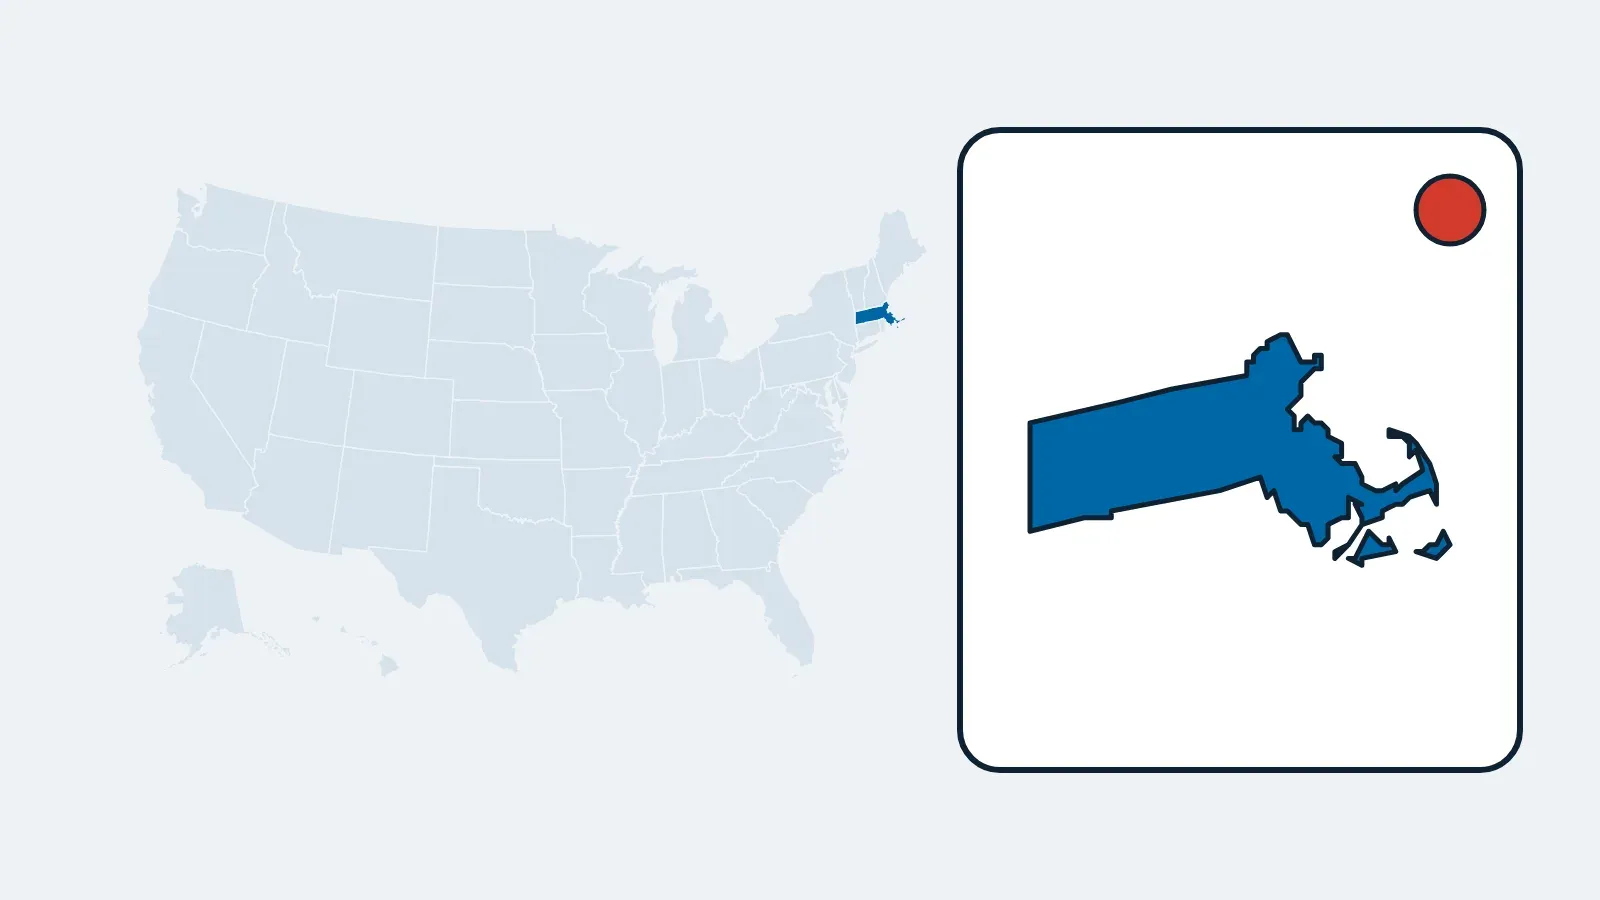
Massachusetts policy rules
State schedule- UM coverage rule
- Required
- Minimum liability
- 25/50/30Policies written or renewed from July 1, 2025; plus $8,000 PIP
- UM/UIM rule
- Required, 25/50 minimumCompulsory part of every policy
- Insurer cancellation notice
- 20 daysSame for nonpayment; only for reasons in 211 CMR 97.03; pro rata refund
- Nonrenewal notice
- 45 daysAgent must forward within 15 days (Division of Insurance bill of rights)
- Regulator
- Massachusetts Division of Insurance
The compulsory parts and their limits
The Massachusetts policy is organized in numbered parts, and four of them are required by law. Chapter 275 of the Acts of 2024 raised the minimums in Chapter 90, Section 34A. The Division of Insurance's filing guidance notice 2025-A, dated January 29, 2025, applied the new figures to policies written or renewed on or after July 1, 2025.
| Coverage | Minimum |
|---|---|
| Bodily injury to others | $25,000 per person / $50,000 per accident |
| Personal injury protection (PIP) | $8,000 per person |
| Bodily injury caused by an uninsured auto | $25,000 per person / $50,000 per accident |
| Damage to someone else's property | $30,000 per accident |
If your policy last renewed before July 1, 2025, its declarations page may have shown lower figures; the new minimums apply from your first renewal on or after that date. The limits gap worksheet shows how far even the new limits go in a serious crash. See personal injury protection for how PIP works.
Uninsured motorist coverage cannot be rejected
Because bodily injury caused by an uninsured auto is one of the compulsory parts, every Massachusetts policy includes it at no less than $25,000 per person and $50,000 per accident. There is no rejection form for this minimum layer. Higher limits and other optional parts are your choice. See Part C for how the standard form describes this coverage; Massachusetts uses its own policy wording, so read your policy for the exact terms.
When a Massachusetts insurer can cancel your policy
The Division of Insurance's regulation on cancellation, 211 CMR 97.00, limits an insurer's midterm cancellation to a short list of grounds. They include:
- Nonpayment of premium.
- Fraud or material misrepresentation in the application or the renewal.
- Suspension or revocation of the license or registration of the named insured or a regular household driver.
- Refusal to allow a vehicle inspection the insurer asked for under Chapter 90, Section 34O.
The regulation also lets an insurer cancel within 90 days after a renewal takes effect in two cases: a general reduction in its Massachusetts auto business allowed under the law, or your failure to return a renewal application at least 30 days before the old policy expired.
Under Chapter 175, Section 113A, the written notice must reach you, or be mailed by first-class mail, at least 20 days before the cancellation date, and a mailed notice counts only if the insurer gets a postal certificate of mailing. The notice must give a specific reason; "underwriting reasons" is not enough. A nonpayment notice must state the amount due, and paying the full amount by the effective date stops the cancellation. The insurer must also report the cancellation to the Registry of Motor Vehicles.
Section 113A also sets the refund. When the insurer cancels, you get a pro rata return of premium. When you cancel, the refund is reduced by the short-rate table set by the Commissioner. The cancellation refund worksheet helps you estimate both.
Renewal and nonrenewal in Massachusetts
The Division's consumer bill of rights says an insurer that will not renew must send notice at least 45 days before the policy expires, to you or your agent, with its reason. An agent who receives the notice must pass it to you within 15 days unless you have already moved to another company. Reasons such as at-fault accidents or traffic violations can support a nonrenewal.
Where to ask and complain
- Check the notice. Look for the specific reason, the effective date and, for nonpayment, the amount due.
- Pay any deficiency before the effective date if the reason is unpaid premium.
- Contact the Division of Insurance at 877-563-4467 or file a complaint through mass.gov.
- Line up replacement coverage before the end date; see lapse and reinstatement.
Policyholder questions
What are the minimum car insurance limits in Massachusetts now?
For policies written or renewed since July 1, 2025: $25,000/$50,000 bodily injury to others, $30,000 property damage, $8,000 PIP, and $25,000/$50,000 uninsured motorist coverage.
Can I drop uninsured motorist coverage in Massachusetts?
No. Bodily injury caused by an uninsured auto is a compulsory part of every Massachusetts policy at the minimum limits.
How much do I get back if my Massachusetts insurer cancels?
A pro rata return of premium under Chapter 175, Section 113A. If you cancel, the refund follows a short-rate table instead. See cancelling your policy.
Sources
- Massachusetts Division of Insurance — Filing Guidance Notice 2025-A, new motor vehicle mandatory coverage limits (January 29, 2025)
- Massachusetts General Laws, Chapter 175, Section 113A — Motor vehicle policy cancellation and refunds
- 211 CMR 97.03 — Policy cancellation
- 211 CMR 97.04 — Cancellation notices
- Massachusetts Division of Insurance — Consumer Bill of Rights for Automobile Insurance
Facts on this page were checked against these sources on November 15, 2026. Massachusetts raised its compulsory bodily injury, uninsured motorist and property damage limits for policies written or renewed from July 1, 2025.
Request policy quotes
Answer six questions about the policy you need. PolicyBrook passes the request to licensed insurance agents and insurers who can quote it; you compare and decide.
- The policy you need. Cars, drivers, coverage and ZIP.
- Your contact details and consent to be contacted.
- A licensed insurance agent or insurer contacts you with a quote. Nothing is bound until you sign and pay.
PolicyBrook is not paid by you. The licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Related readings
-
Policy event
Insurer cancellation
After 60 days, only listed reasons; 10 to 60 days' notice by state, and how to appeal.
-
Endorsement
Personal injury protection
No-fault injury coverage: $10,000 required in Florida, rejectable in Texas, offered in Washington.
-
Policy part
Uninsured motorists (Part C)
Four kinds of uninsured vehicle, who is insured, limits, 60-day trial right after arbitration, state rules.