State: Required
Maine: The Rules Your Auto Policy Must Follow
Maine sets some of the higher minimum limits in the country, requires uninsured motorist and medical payments coverage on every policy, and gives you a right to a hearing when a company cancels or will not renew. Here is what that means for your policy.
By PolicyBrook Editorial Team Updated 4-minute read
Declarations
Maine- UM/UIM rule
- Required
- Minimum liability
- 50/100/25
- Insurer cancellation notice
- 20 days (10 nonpayment)
- Nonrenewal notice
- 30 days
In brief
A Maine policy must carry at least $50,000/$100,000/$25,000 of liability coverage and $2,000 of medical payments coverage. Uninsured vehicle coverage, which also covers underinsured and hit-and-run drivers, is required: you can lower it in writing but not below the minimum. After 60 days, an insurer may cancel only for reasons listed in 24-A M.R.S. §2914, with 20 days' notice, or 10 days for nonpayment. Nonrenewal takes 30 days' notice with an explicit reason, and you can ask the Superintendent of Insurance for a hearing.
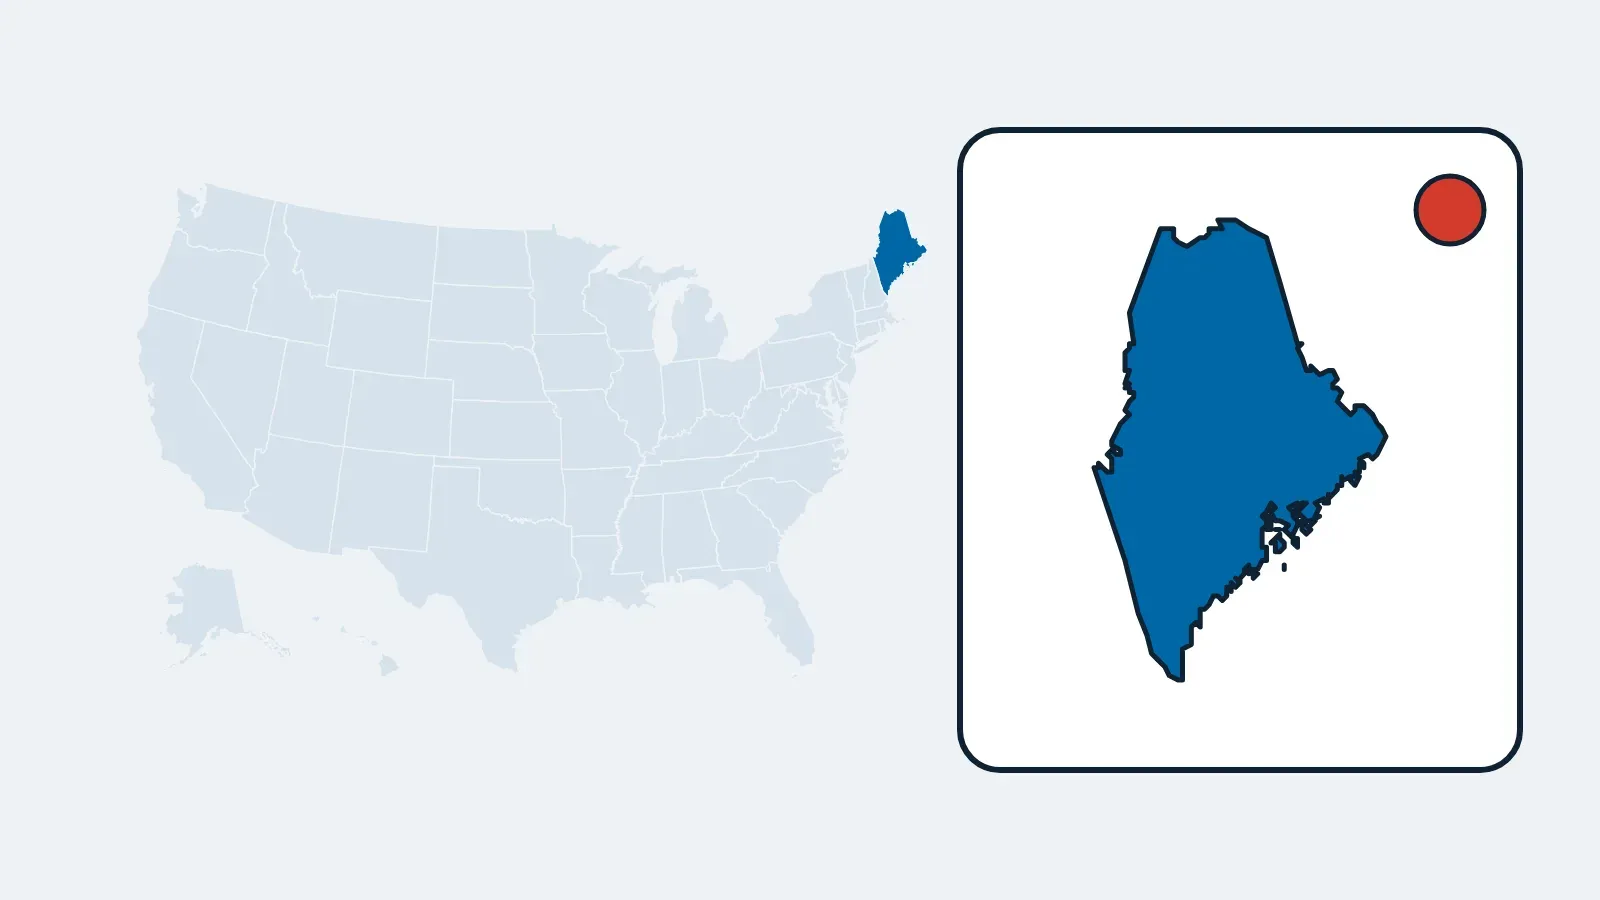
Maine policy rules
State schedule- UM coverage rule
- Required
- Minimum liability
- 50/100/25Plus $2,000 medical payments; a $125,000 single limit also qualifies
- UM/UIM rule
- Required, 50/100 minimumMatches liability limits unless lowered in writing (24-A M.R.S. §2902)
- Insurer cancellation notice
- 20 days; 10 days for nonpaymentAfter 60 days, only for reasons in 24-A M.R.S. §2914; hearing right
- Nonrenewal notice
- 30 daysExplicit reason required; hearing request within 30 days
- Regulator
- Maine Bureau of Insurance
Minimum limits and proof on a Maine policy
Under 29-A M.R.S. §1605, a Maine policy must provide at least $50,000 for bodily injury to one person, $100,000 for bodily injury to more than one person in an accident, and $25,000 for property damage: 50/100/25 on your declarations page. The Bureau of Insurance says a $125,000 combined single limit also meets the requirement. The same section requires at least $2,000 of medical payments coverage, the part of the policy described in Part B.
Proof can be electronic. 29-A M.R.S. §1601 accepts an image of your insurance card on a phone or other portable device, and showing the device to an officer is not consent to search anything else on it.
Uninsured vehicle coverage is required
24-A M.R.S. §2902 bars an insurer from issuing a motor vehicle liability policy for a car registered or principally garaged in Maine unless it includes uninsured vehicle coverage. In Maine that one coverage protects you against uninsured, underinsured and hit-and-run drivers.
By default, the coverage matches your bodily injury liability limits. A named insured may reject that matching amount and choose lower limits, in writing on the insurer's form, but never below the 50/100 minimum. There is no way to remove the coverage entirely, which is why this site lists Maine as a state where UM is required. If the insurer has no signed form before the policy starts, the higher amount applies. See Part C for what it pays.
When a Maine insurer can cancel your policy
During the first 60 days of a new policy, the insurer may cancel for any reason, as long as you receive the notice before the 60th day. After that, and for renewal policies, 24-A M.R.S. §2914 allows cancellation only for:
- Nonpayment of premium.
- Fraud or material misrepresentation affecting the policy or a claim.
- A violation of the policy's terms or conditions.
- Suspension or revocation of the driver's license of the named insured or a household or regular driver, with some exceptions for certain first or second suspensions.
Under §2915, you must receive the notice at least 20 days before the cancellation date, or at least 10 days when the reason is nonpayment. Unless the policy is still in its first 60 days, the notice must state the reason and your right to request a hearing before the Superintendent of Insurance within 30 days. The insurer also cannot change your policy during its term unless you both agree; an agreed change is not a cancellation.
The statutes reviewed for this page do not set a refund method, so your policy's cancellation clause controls the return of unearned premium. The cancellation refund worksheet helps you check the figure.
Renewal and nonrenewal in Maine
Under 24-A M.R.S. §2917, you must receive a nonrenewal notice at least 30 days before the policy expires. The reason must come with it and must be explicit: phrases such as "underwriting reasons," "loss record" or "credit report" do not count on their own. The notice must also tell you about your right to a hearing within 30 days.
No notice is needed if the insurer has shown it is willing to renew, if you do not pay a premium due, or if the policy moves to an affiliate, in which case you must be told before renewal of any less favorable changes. The Bureau of Insurance says the cancellation grounds can also support nonrenewal, along with certain violations or accidents in the 36 months before expiration, such as operating under the influence or two or more qualifying accidents.
Where to ask and complain
- Read the notice. Check the date you received it, the effective date and whether the reason is specific.
- Request a hearing within 30 days if you believe the reason is wrong or does not fit the law.
- Contact the Maine Bureau of Insurance at 800-300-5000 or through its complaint page on maine.gov.
- Arrange new coverage before the end date; see lapse and reinstatement.
Policyholder questions
Can I reject uninsured motorist coverage in Maine?
Not entirely. You can reject coverage equal to your liability limits and choose lower limits in writing, but not below $50,000 per person and $100,000 per accident.
Can a Maine insurer cancel my policy after a claim?
After the first 60 days, only for nonpayment, fraud or misrepresentation, a policy violation, or a license suspension or revocation. A claim history may matter at renewal instead; see nonrenewal.
Can I contest a Maine cancellation or nonrenewal?
Yes. Apart from cancellations in the first 60 days, you can ask the Superintendent of Insurance for a hearing within 30 days after you receive the notice.
Sources
- 24-A M.R.S. §2914 — Automobile policy cancellation
- 24-A M.R.S. §2915 — Notice of cancellation
- 24-A M.R.S. §2917 — Notice of intention not to renew
- 24-A M.R.S. §2902 — Uninsured vehicle coverage
- 29-A M.R.S. §1605 — Minimum insurance requirements
- 29-A M.R.S. §1601 — Proof of insurance, including electronic proof
- Maine Bureau of Insurance — Cancellations, nonrenewals and hearings
Facts on this page were checked against these sources on November 15, 2026. Maine's medical payments requirement sits in the same statute as its liability minimums, 29-A M.R.S. §1605.
Request policy quotes
Answer six questions about the policy you need. PolicyBrook passes the request to licensed insurance agents and insurers who can quote it; you compare and decide.
- The policy you need. Cars, drivers, coverage and ZIP.
- Your contact details and consent to be contacted.
- A licensed insurance agent or insurer contacts you with a quote. Nothing is bound until you sign and pay.
PolicyBrook is not paid by you. The licensed insurance agents and insurers who contact you set their own prices and terms. How we make money.
Related readings
-
Policy event
Insurer cancellation
After 60 days, only listed reasons; 10 to 60 days' notice by state, and how to appeal.
-
Policy event
Nonrenewal
Notice periods from 15 to 75 days, reasons states bar, and how to ask the regulator for review.
-
Policy part
Uninsured motorists (Part C)
Four kinds of uninsured vehicle, who is insured, limits, 60-day trial right after arbitration, state rules.